This notion of volatility as irritation or a phase as opposed to true risk is not to be taken cavalierly in the face of an extraordinary global pandemic. To be sure, there is no real roadmap for where we find ourselves now. Many illiquid businesses will fold, so will many previously liquid businesses. Unemployment has already begun to soar, consumer behaviors have changes and will be permanently altered in some ways. Millennials are now twice bitten by 100-year events since entering the workforce and beginning to save. They are likely to be risk averse for the rest of their lives.
The world that will emerge after the pandemic subsides will, more likely, face a challenging economic recovery, rather than the sharp rebound many investors continue to hope for. But, no one really know what is on the other side of this and no business will go unaffected. Those who proclaim differently shouldn’t be trusted.
So, we will have volatility, but volatility, in and of itself, if perceived correctly, it is not inherently bad. In fact, volatility can often be an exceptional opportunity for price sensitive, long term investors to upgrade their portfolios. The essential goal of investing is to earn risk adjusted returns that are superior, over time, to those on risk free assets.
Superior returns come with the assumption of reasonable business risks. In due time we will once again be able to make reasonable assumptions about business risk. In the current circumstances, of course, it is impossible to decipher the near-term earnings prospects of most companies, but it is not impossible to ascertain an approximate “through-cycle” estimate of earnings power for quality companies with sound balance sheets and unimpaired end markets. Then, one can discount those estimates based on several different scenarios. If fear induced volatility in the market creates a significant gap between the current price and the intrinsic value derived from such exercises it yields an attractive entry point for long term investors.
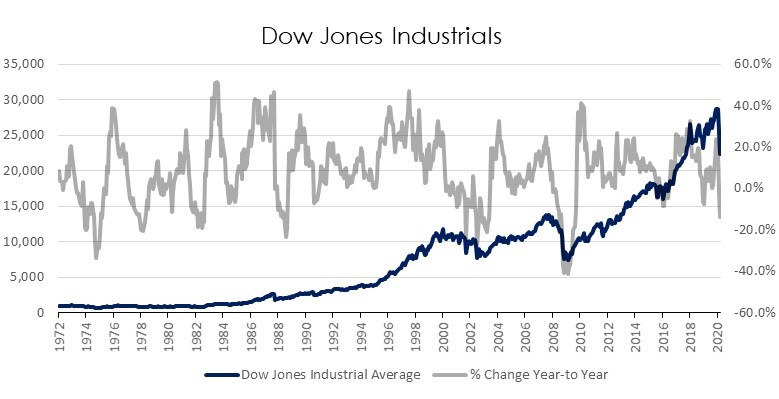
“Markets fluctuate,” said Bernard Baruch, and indeed they do. In both directions. Over the long term, that direction has been primarily up.